
[adrotate group=”1″]
Netflix takes the wrapped off its newest tier - “Basic with Ads” tier tomorrow at a price tag of $5.99 and show up to 5 minutes of ads each hour. The advertising has been talking about it for months in anticipation on its impact for and brands.
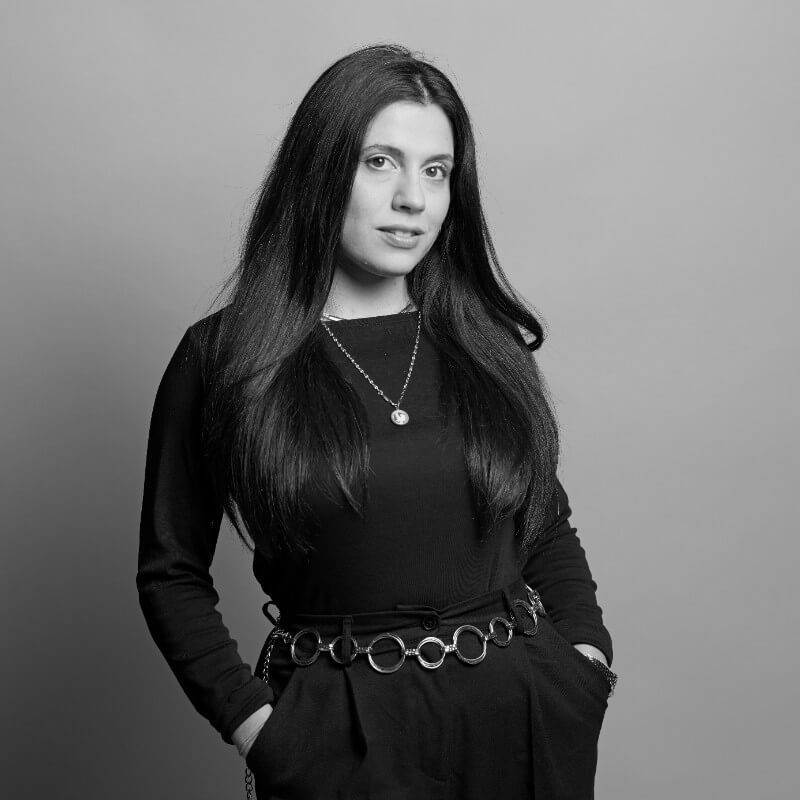
For our latest edition of Industry Opinion, we caught up with Marissa Cristiano, Group Account Director, Cossette Media [TCO]
First thoughts on what Netflix ad-supported tier?
Marissa - The initial reaction is excitement. The enthusiasm for releases on the platform and its stickiness is something that brands and advertisers have been asking for for years.
That said, there is a bit of sticker shock around the initial price tag at $65 CPM. We see average costs hover around $30-$40 with other CTV partners that offer a lot more data targeting than what Netflix is offering at the moment. Because of their user base and content, we do expect a bit of a premium, but a $65 CPM may make it less accessible to small-mid size brands, or force them to approach a Netflix buy as an alternative to other high-impact brand activity like takeovers or sponsorships.
Is this good for brands?
Marissa - The short answer is yes. Brands will have to be really intentional with how they show up on Netflix. Netflix has created such a user-first ecosystem, and clearly intends to maintain this ethos with its ad-supported rollout. If brands want to be successful on the platform, they will need to show up authentically with the same mindset.
What’s missing now for brands is a form of more meaningful measurement to gauge the success or additional value of adding Netflix to their media mix. Returns - in the form of incremental audience or awareness - may be felt initially with a new presence on the platform, but they’ll have to offer some more robust measurement in order for brands to buy in for the long term.
What impact will this have on the industry?
Marissa - It’s placing CTV and digital streaming at the forefront as a foundational part of a media plan. For a long time, CTV has often been treated as an incremental reach driver to broadcast activity or a way to reach cord-cutters and cord-nevers. The release of ads on Netflix, with a premium price tag attached, is really declaring the value of non-linear television.
I think this may also spur a greater appreciation of the value of contextual. Netflix is only offering genre targeting and not any deeper data targeting options based on user behaviour (which we’ve seen other CTV players do as the space has matured). If brands see a positive uptick in their perception by being on the platform with contextual targeting alone, much less paying a premium cost for contextual, this may inspire a greater conversation about the value of contextual for upper-funnel activity - a timely conversation with the looming death of cookies.
What impact will this have on consumers?
Marissa - Consumers are overwhelmed by a segmented streaming landscape that is largely subscription based. Cord-cutting is no longer a cost-saving exercise as subscriptions across multiple providers can exceed the cost of a cable package. It’s now about accessing the content that you want. Having a cheaper ad-supported option on Netflix democratizes access to content, and since consumers are buying into a less premium option they may be more receptive to the ads on screen.
The potential for ads also changes the binge-watching experience that Netflix is famous for. By breaking up the previously uninterrupted flow of streaming, binge-watching will now become a premium experience.
What are your thoughts on the proposed frequency caps that Netflix plans to implement?
Marissa - This is in line with Netflix’s user-first ethos. Frequency caps are meant to provide a user-first experience and not overwhelm ad-supported subscribers with ads.
However, frequency, especially on the big screen, is an essential part of driving upper-funnel metrics like recall, awareness and favourability. With multiple brands active and only three potential exposures per day, there is a lot of room for competition among brands and lower frequency. Netflix doesn’t currently have any advanced analytics to measure brand lift or brand health, but one of the potential outcomes is that frequency caps may get in the way of moving the needle on brand metrics.
Targeting, (in phase 1) will be limited to Netflix’s Top 10 TV shows in each region as well as content genres like action, drama, romance and sci-fi.
Marissa - It’s definitely positioning Netflix as an upper-funnel driver.
Brands are used to having a ton of control over where they appear and prioritizing brand safety in digital environments, so the broadness of genre targeting may be off-putting for some at first. Other players in the space have prioritized user targeting over genre targeting. Genre targeting leaves a lot of room for ambiguity. For example, if you’re targeting comedy, that could be anything from Seinfeld to Emily in Paris. I could imagine a menswear brand for example wanting to target comedy because of the high index against their consumers but not wanting to run against a show like Emily in Paris.
I think the eventual evolution of this is custom show segments and being able to curate a cluster of programs that you’d like to have your brand appear against.
Netflix is launching with a minimum commitment agency commitment.
Marissa - The idea here is clear- Netflix wants to launch with large, established brands that have huge buying power. Small to mid-size brands will have a tougher time getting a first-movers advantage on the platform. It’s an astronomical amount for most companies, especially in the Canadian market and within the context of how much most brands are currently investing in CTV or streaming services in their media mix.
What is the benefit to a brand to be one of the first to advertise on Netflix?
Marissa - First- movers advantage. Brands can position themselves as an innovator in the digital space and having the ability to move fast. They’re also the first to benefit from the incremental reach in a new environment.
Netflix has not promoted this new ad-supported tier to consumers (in a meaningful way), what impact could this have on November 1st?
Marissa - It’s hard to tell at this stage. It may result in an initial loss of premium subscribers as they transition to the ad-supported tier. It may also usher in a new wave of consumers who were previously not subscribing due to upfront cost.
We also have to take the “extra home” fees Netflix has discussed into consideration. Consumers are used to sharing one premium subscription under multiple profiles. The “extra home fee,” which would block your streaming if you are trying to access streaming from an address other than your home address, may be the thing that gets most consumers off someone else’s profiles and onto a less expensive ad-supported tier.
Who will be the buyers of the $5.99 plan?
Marissa - I think the subscriber base will be similar to how we see with free/premium services like Spotify and YouTube.
More casual viewers and backgrounders - consumers who are watching a couple hours a week or who have re-runs of old favourites playing in the background as they do chores will be less bothered by an ad breaking up their programming, especially considering the light frequency of ads on platform.
Likely the binge-watchers who are watching many hours a night and frequently looking for their next show to discover on Netflix will value an un-interrupted ad-free experience.
Interested in being a guest on a future edition of Industry Opinion?
[adrotate banner=”10″]
[adrotate banner=”4″]
[adrotate banner=”6″]
